Asia-Pacific Airlines Prioritise Long-Haul Routes as Fuel Costs Rise
Asia-Pacific carriers are reducing regional and short-haul flight frequencies. This adjustment protects long-haul networks as jet fuel prices approach US$160 a barrel, eroding profit margins. Alton Aviation Consultancy reported this on 2 September 2026.
Fuel Costs Drive Network Adjustments
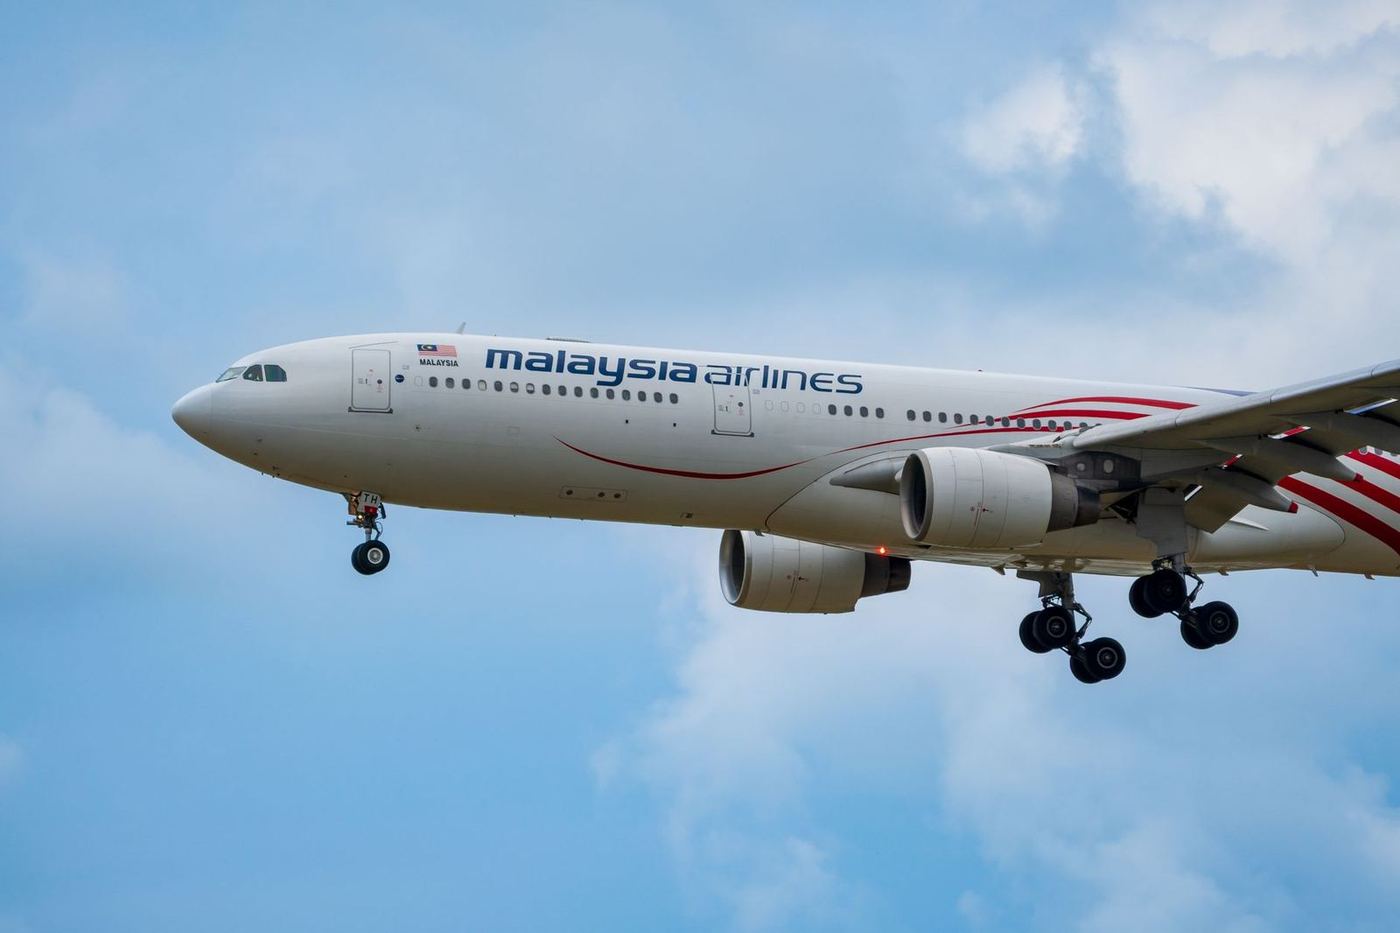
Asia-Pacific airlines are curtailing regional and short-haul flights. This strategy aims to safeguard their long-haul networks. The adjustment follows jet fuel prices nearing US$160 per barrel, which reduces profit margins as the autumn flying season begins. Alton Aviation Consultancy, on 2 September 2026, provided these insights.
Clark Johns, a director at the consultancy based in Auckland, noted regional jet fuel traded near US$160 a barrel on 21 August. This price marks a 75 per cent increase compared to a year prior. The crack spread between crude and jet fuel has consistently stayed between US$60 and US$65.
Revised Profit Forecasts for Carriers
This operational shift reflects a wider industry reaction to increasing expenses. The International Air Transport Association’s (IATA) June 2026 Global Outlook for Air Transport report shows revised profit expectations. Asia-Pacific carriers now anticipate a net profit of approximately US$6.6 billion for 2026. This figure represents a decrease from US$9.8 billion in 2025.
Profit per passenger is also projected to fall to US$3.40, down from US$5.30. Globally, the IATA report nearly halved the year’s profit forecast. The worldwide projection moved from US$41 billion to US$23 billion, based on jet fuel averaging US$152 a barrel throughout the current year.
Strategic Flight Decisions and Market Shifts
Airlines are making targeted reductions, primarily on routes with multiple daily services. This allows them to consolidate passengers onto fewer flights. Johns explained that a single daily flight to a key long-haul destination, such as London, remains crucial for network transit. He does not consider these changes a permanent structural shift.
Recent regional transit flows have favoured Asia due to capacity reductions by Gulf carriers. Demand for non-stop Asia to Europe services and connections through Changi, Hong Kong, and mainland Chinese hubs held firm. Singapore Airlines, Cathay Pacific, and mainland Chinese operators absorbed much of this redirected traffic.
Thai Airways also expanded its European network from Suvarnabhumi, gaining some benefit. Chinese carriers further gained an advantage by overflying Russian airspace, which other airlines avoid, shortening trip times and reducing fuel burn.
Uneven Impact and Future Outlook
The pressure from higher fuel costs affects airlines unevenly. Full-service carriers, with substantial business and premium traffic, can more readily pass increased fuel expenses into fares. Conversely, low-cost and ultra-low-cost operators face greater demand challenges.
A 20 to 30 per cent fare increase often deters price-sensitive leisure and visiting friends and relatives (VFR) travellers. With fuel prices remaining volatile and a backlog of over 16,000 aircraft deliveries, airlines in the region plan for extended uncertainty. Carriers are compelled to operate older jets for longer periods.
This situation demands greater planning flexibility and adaptive decisions concerning fleet management and balance sheet cash holdings. Travellers should expect continued route adjustments and potential fare increases, particularly in the budget segment, as the industry navigates these conditions.
Get The Post.
The global travel stories that matter, three mornings a week. Free.