Airlines Face $11 Billion Engine Cost Surge Amid Reliability Concerns
The International Air Transport Association forecasts global airline net profits to halve in 2026, partly due to ongoing issues with next-generation aircraft engines and supply chain disruptions.
Industry Profit Outlook Dims for 2026
The International Air Transport Association (IATA) projects a significant decline in global airline net profits for 2026, anticipating a drop from $45 billion in 2025 to $23 billion. This reduction is expected to see net margins contract from 4.2% to 2.0%.
A substantial portion of this financial strain, estimated at $11 billion in additional costs, stems from persistent engine durability problems and disruptions within the supply chain, as reported by IATA.
Willie Walsh, IATA's CEO, highlighted a notable disparity between the robust financial performance of engine manufacturers and the operational challenges and increased expenditures faced by airlines.
Persistent Engine Durability and Supply Challenges
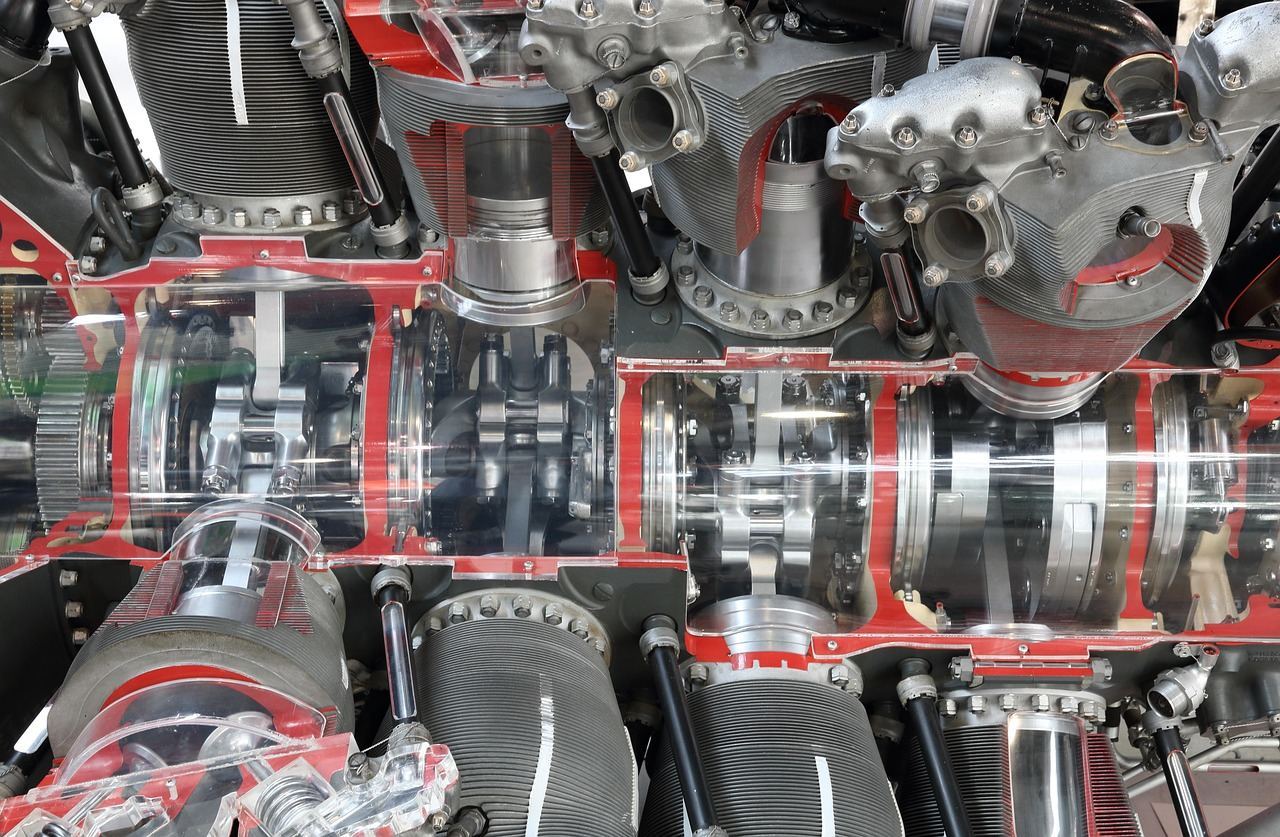
The core issues impacting airline operations are a combination of supply chain weaknesses and durability concerns with modern, fuel-efficient engines. The loss of engine manufacturing capacity during the COVID-19 pandemic has exacerbated these problems, making recovery difficult.
Specific engine types, including the Pratt & Whitney GTF turbofans, which power Airbus A220, A320 series, and Embraer E-Jet aircraft, and the Rolls-Royce Trent 1000 for the Boeing 787 Dreamliner, have been particularly affected.
Groundings of Pratt & Whitney GTF-powered aircraft peaked in March 2025, with 648 units—28% of the GTF fleet—out of service awaiting maintenance or spare parts. These operational constraints are expected to continue into 2027, with Azul CEO John Rodgerson noting that new engines are “not lasting as long” as anticipated.
Manufacturer Responses and Lingering Constraints
In response to these challenges, engine manufacturers are investing heavily to boost production and repair capacities. Pratt & Whitney has introduced the improved GTF Advantage, while Rolls-Royce is delivering the Trent 1000 XE, which it claims offers triple the on-wing durability of its predecessor.
Despite these efforts, the overall global engine fleet remains constrained, according to Andy Cronin, CEO of lessor Avolon, who noted only “incremental improvement” year-on-year.
United Airlines CEO Scott Kirby believes engine issues will continue to be the industry's primary constraint for at least the next five years, commending GE and Pratt & Whitney for their efforts while expressing dissatisfaction with Rolls-Royce.
Asian Operators Grapple with Fleet Utilisation
The global strain on engine reliability has direct implications for Asian carriers, many of whom operate extensive fleets of the affected aircraft types. Airlines across the region, including those flying Airbus A320neo family jets and Boeing 787 Dreamliners, face increased operational costs and potential disruptions to their flight schedules.
With grounded aircraft persisting into 2027, as reported by Reuters in June, Asian airlines may experience reduced capacity or delays in expanding their networks, potentially impacting passenger fares and cargo rates across key regional and international routes.
The financial burden, estimated by IATA to be $11 billion in additional costs globally, could temper growth strategies for operators in a highly competitive market like Asia, where efficient fleet utilisation is crucial for profitability.
Get The Post.
The global travel stories that matter, three mornings a week. Free.